Para quienes desean conocer las opciones de juego disponibles en el mercado español, es importante consultar información actualizada sobre los casinos con licencia en España y los requisitos que deben cumplir los operadores. Verificar la autorización de la DGOJ ayuda a comprender mejor el marco legal y las medidas de protección aplicables.

Los métodos de pago digitales ofrecen distintas posibilidades para gestionar depósitos en plataformas de entretenimiento online. Una guía sobre los casinos online que aceptan Neteller en España permite conocer las características de este monedero electrónico, sus condiciones de uso y los aspectos que conviene revisar antes de realizar una transacción.

Los plazos de procesamiento de los pagos son un aspecto importante al analizar los servicios de entretenimiento digital. Consultar información sobre los casinos online que pagan rápido en España ayuda a comprender las diferencias entre los métodos de retirada, los tiempos de verificación y las condiciones que pueden afectar a cada operación.

Las soluciones de prepago permiten controlar el importe destinado a las transacciones digitales sin compartir directamente los datos bancarios en cada operación. Conocer las características de los casinos con Neosurf puede ayudar a entender cómo funciona este método, qué limitaciones presenta y qué condiciones deben comprobarse antes de utilizarlo.

Las tarjetas bancarias siguen siendo una de las opciones habituales para efectuar pagos por internet, aunque su disponibilidad depende de cada plataforma y entidad financiera. Una revisión de los casinos online con Mastercard en España permite identificar los aspectos relacionados con la aceptación de tarjetas, la seguridad de las transacciones y las posibles comisiones.

Los juegos de demostración ofrecen una forma de familiarizarse con las reglas y mecánicas de diferentes títulos sin comprometer dinero real. Explorar información sobre los juegos de casino gratis sin registro ayuda a distinguir las versiones de prueba de las modalidades con dinero real y a comprender las condiciones de acceso a cada servicio.

Las aplicaciones financieras incorporan herramientas para administrar pagos digitales y consultar movimientos desde un mismo entorno. Antes de utilizar una plataforma de entretenimiento, puede resultar útil revisar la información disponible sobre los casinos online que aceptan Revolut en España, prestando atención a la compatibilidad de las operaciones, las restricciones aplicables y la regulación del operador.

La compatibilidad con tarjetas de pago es uno de los factores que los usuarios suelen comprobar al evaluar servicios digitales. Una guía sobre los casinos online que aceptan Mastercard en España permite conocer los procedimientos habituales de depósito, las posibles limitaciones bancarias y las medidas de seguridad que deben tenerse en cuenta.

Los sistemas de pago bancario online facilitan la gestión de transferencias y pueden ofrecer procesos de autenticación integrados. Para comprender mejor sus características, conviene consultar información sobre los casinos online que aceptan Trustly en España, así como verificar la disponibilidad del servicio, las condiciones de las operaciones y la licencia correspondiente de cada operador.

La rapidez de una retirada depende de factores como el método de pago elegido, las verificaciones de identidad y las políticas de procesamiento de cada plataforma. Informarse sobre los casinos online con retiros rápidos en España permite entender qué plazos pueden aplicarse y por qué una transferencia no siempre se completa de forma inmediata.

Al comparar plataformas digitales, es recomendable revisar tanto los procedimientos de retirada como los requisitos necesarios para autorizar cada transacción. La información sobre los casinos con retirada inmediata en España ayuda a conocer las diferencias entre los tiempos de aprobación y los plazos bancarios, que pueden variar según el proveedor y las comprobaciones de seguridad.

Los límites de depósito varían entre plataformas y métodos de pago, por lo que conviene conocer las condiciones antes de efectuar cualquier operación. Una guía de casinos online con depósitos de diferentes importes en España permite comparar los mínimos establecidos y comprender las restricciones aplicables, además de recordar la importancia de fijar un presupuesto responsable.

La seguridad y la transparencia son criterios esenciales al evaluar cualquier servicio de entretenimiento online. Consultar una selección de casinos online fiables en España puede ayudar a identificar los elementos que conviene verificar, como la licencia de la DGOJ, las condiciones de uso, la protección de los datos personales y los mecanismos de atención al usuario.

Los requisitos de depósito mínimo y las opciones de pago pueden variar considerablemente entre operadores. Para conocer mejor estas diferencias, resulta útil consultar información sobre los casinos online con depósito mínimo de 20 euros en España, prestando atención a las condiciones de las transacciones, los requisitos de acceso y la autorización legal de cada plataforma.

Los pagos mediante dispositivos móviles permiten realizar determinadas transacciones sin introducir manualmente los datos de la tarjeta en cada ocasión. Una guía sobre los casinos online con Apple Pay en España ayuda a comprender la compatibilidad de este sistema, sus requisitos de seguridad y las condiciones que deben verificarse antes de utilizarlo en servicios digitales.

Imagine stepping into a coffee shop, tapping a sleek plastic card, and watching your crypto balance transform into a latte without a single fiat conversion delay. The promise of crypto debit cards feels like sci‑fi made real, yet the market is a tangled jungle of platforms each shouting “the best.” Navigating that noise requires a clear lens, a way to separate flash from substance before you hand over your hard‑earned tokens.

When you start hunting for the right crypto card, the first instinct is to glance at flashy rewards and ignore the fine print. That’s a mistake; a hidden fee can erode a month’s worth of gains. A solid starting point is browsing trusted resources like cryptocardbasics.com, where basics are broken down without jargon. From there, you can map your priorities—speed, security, or spend‑ability—against what each provider actually delivers. That diligence pays off when you compare the subtle differences between providers.

Core Features to Evaluate

Cryptocurrency cards differ primarily in the assets they support. Some restrict you to a handful of top‑tier coins, while others embrace dozens of altcoins and stablecoins. The breadth of supported tokens determines how often you’ll need to juggle wallets before a purchase. If your portfolio spikes with lesser‑known gems, a platform limited to Bitcoin and Ethereum will force constant conversion, costing time and possibly small fees. Choosing a platform that mirrors your asset mix prevents unnecessary swaps and keeps your portfolio intact.

If you value instant conversion, look for cards that process transactions on the blockchain itself rather than relying on a centralized processor. On‑chain swaps can shave seconds off the checkout experience, but they may require a small network fee. Conversely, cards that batch conversions off‑chain often bundle costs, resulting in a more predictable expense. Some users even trade off a modest fee for the certainty of a fixed rate. Decide whether speed or cost consistency wins your vote before you sign up.

Consider the card’s integration with existing financial apps. Platforms that sync with popular budgeting tools let you track crypto spend alongside fiat expenses, painting a holistic picture of cash flow. Without this harmony, you might end up guessing where your tokens vanished after a weekend of dining out. Seamless reporting isn’t just a nice‑to‑have; it’s a guardrail against accidental overspending. A unified view also helps you spot irregular spend patterns before they become costly.

Meanwhile, the underlying network choice matters. Cards built on slower chains can lag during peak congestion, leaving merchants with a “transaction pending” message that feels forever. Speedier ecosystems like layer‑2 solutions or sidechains often deliver a smoother checkout, though they sometimes sacrifice decentralization. Opting for a sidechain can shave seconds off each purchase, a marginal gain that adds up. Weigh the trade‑off between raw performance and the philosophical foundation of the blockchain you trust.

A robust customer support framework rounds out the feature set. When a transaction fails or a token freezes, rapid assistance can mean the difference between a missed flight and a missed payment. Look for platforms that offer 24/7 chat, clear escalation paths, and multilingual staff. Support that’s merely an email ticket system buried under generic FAQs rarely meets the demands of active crypto users. Responsive support teams often provide live demos that walk you through the most common hiccups.

Security and Privacy Considerations

Because crypto cards sit at the intersection of digital assets and traditional payment rails, they inherit security concerns from both worlds. Multi‑factor authentication, hardware wallets, and biometric lockouts are baseline defenses you should expect. Anything less feels like a porch light left on in a dark neighborhood; it simply invites unwanted attention. Strong encryption alone won’t shield you if the back‑end infrastructure is flawed.

Yet even the strongest encryption can be undone by careless user habits. Storing recovery phrases on your phone or sharing PINs with friends undermines the platform’s protective layers. A disciplined approach—offline backups, password managers, and regular audits—keeps the security narrative in your favor rather than the hacker’s. A habit of rotating passwords every few months further fortifies that armor.

Notably, some providers offer insurance coverage that kicks in when a breach occurs, akin to a safety net for your digital vault. This insurance isn’t a blanket guarantee; it typically applies to specific scenarios and may involve claim procedures. Still, the existence of such a program signals a company’s confidence in its own defenses. Check the policy fine print to see which incidents are actually covered.

Behind every secure card lies a compliance framework that can affect anonymity. Know‑Your‑Customer (KYC) and Anti‑Money‑Laundering (AML) processes often require identity verification, turning a pseudonymous crypto experience into a trackable one. If privacy is a top priority, research how much personal data the issuer retains and whether they share it with third parties. If anonymity outweighs compliance for you, seek providers that offer minimal data retention.

Often, the most overlooked threat is the merchant itself. Some retailers still process crypto payments through intermediaries that store transaction hashes, opening a backdoor for future data mining. Choosing cards that route payments directly to the blockchain reduces this exposure, but demands that merchants support such direct paths, a rarity in many regions. Direct blockchain routing also reduces the chance of transaction replay attacks.

User Experience and Accessibility

Rarely does a crypto card feel as intuitive as a mainstream credit card, but the gap is shrinking thanks to mobile‑first design philosophies. Apps that streamline onboarding, auto‑populate address fields, and provide real‑time exchange rates help bridge the learning curve. A clunky interface, by contrast, can discourage even seasoned traders from using the card in everyday life. An onboarding tutorial that walks you through the first transaction can turn curiosity into confidence.

Design Matters

Directly after login, the dashboard should reveal key metrics: balance, pending transactions, and rewards earned, all in a glance. Overloading the screen with charts and jargon forces users to hunt for basic information, a friction point that turns curiosity into abandonment. Simplicity does not mean stripping features; it means curating them for immediate relevance. The layout should also allow one‑tap access to the swap feature, streamlining the process.

Still, the tactile feel of the physical card cannot be ignored. Chip quality, magnetic strip durability, and even the card’s visual aesthetic influence how often you carry it in your wallet. A flimsy card that bends after a few weeks conveys a lack of investment in the product, subtly prompting users to revert to their fiat alternatives. A well‑designed card also fits comfortably in a standard wallet slot, avoiding bulk.

Ultimately, accessibility extends beyond the app into regional availability. Some platforms restrict cards to certain countries, forcing users to rely on proxy services or wait for future rollouts. Global reach matters for digital nomads and travelers who expect seamless card acceptance across borders, just like any airline loyalty card. A card that works in over a hundred countries truly earns the label of global.

Beyond basic spendability, the card’s ability to integrate with decentralized finance (DeFi) platforms can unlock new use cases. Features like automatic staking, yield farming, or token swaps within the app transform a simple payment tool into an active financial engine. If your strategy includes earning passive income, prioritize cards that weave DeFi hooks into their core. These DeFi‑linked perks turn every swipe into a micro‑investment opportunity.

Rewards, Fees, and Hidden Costs

Unlike traditional credit cards that parade cash‑back percentages, crypto cards often sweeten the deal with token‑based rewards. These rewards can fluctuate wildly with market movements, turning a predictable 1% cash‑back into a speculative gamble. Assess whether the allure of a token reward aligns with your risk tolerance before you chase the hype. However, token rewards can be volatile; a sudden dip may erase the perceived gain.

Some platforms levy conversion fees each time you spend a crypto asset, a small bite that adds up over a month of coffee purchases. Others bundle the fee into the exchange rate, making it less visible but no less present. Spotting these hidden costs requires a keen eye on transaction receipts and the platform’s fee disclosure page. Scrutinize the fee schedule before you sign up, because hidden costs quietly erode returns.

Every card issuer also imposes a baseline maintenance charge, often waived after you hit a spending threshold. While a modest monthly fee may seem negligible, it can erode the value of modest rewards, especially if you’re not a high‑spender. Weigh the fee structure against your typical monthly outlay to gauge net benefit. If you’re near the waiver threshold, a few extra purchases can flip the equation.

Those loyalty programs that lock rewards for a period can be a double‑edged sword. On one hand, they encourage long‑term holding of the native token, potentially increasing its value. On the other, they restrict immediate redemption, leaving you with idle assets that could have been deployed elsewhere. Lock‑in periods also limit liquidity, meaning you can’t sell the token when the market spikes.

Most users overlook the impact of merchant fees on the final price. When a retailer accepts crypto, they may pass on a processing charge that appears as a slight markup on your receipt. This practice can neutralize any nominal reward you earn, making the entire transaction essentially cost‑neutral. Being aware of these surcharges lets you decide whether the convenience outweighs the extra cost.

Future Outlook and Choosing Your Card

Few crypto cards have yet proven staying power beyond the initial hype cycle; many launch with fanfare only to fade as market conditions shift. Longevity hinges on the issuer’s ability to adapt to regulatory changes, integrate emerging blockchain standards, and sustain a user‑friendly ecosystem. Providers that weather bearish cycles often emerge stronger, having refined their risk models.

Such adaptability is evident in platforms that regularly roll out software updates, expand token support, and partner with global payment networks. A living product that evolves with the crypto landscape offers a hedge against obsolescence, ensuring your card remains functional as new chains rise. Such evolution signals a commitment to staying competitive as user expectations rise.

While no single card fits every scenario, a pragmatic approach is to list your top three priorities—be it speed, security, or reward type—and match them against the providers that excel in each. Treat the selection process like a portfolio diversification exercise: spread risk, capitalize on strengths, and keep options open. Balancing these factors yields a strategic choice that fits both your lifestyle and investment goals.

Across the board, community feedback serves as a reliable barometer for real‑world performance. Forums, social media threads, and user reviews often surface quirks that official documentation glosses over. Tuning into that collective voice can save you weeks of trial and error. Community sentiment also highlights any recurring support delays or outage patterns.

This final checklist: verify supported assets, test transaction speed, confirm fee transparency, and ensure robust support. With those boxes ticked, you’ll wield a crypto card that truly amplifies your digital spending, not just a flashy novelty. Check each item twice before you commit, and you’ll avoid costly surprises.
Imagine stepping into a coffee shop, tapping a sleek plastic card, and watching your crypto balance transform into a latte without a single fiat conversion delay. The promise of crypto debit cards feels like sci‑fi made real, yet the market is a tangled jungle of platforms each shouting “the best.” Navigating that noise requires a clear lens, a way to separate flash from substance before you hand over your hard‑earned tokens.

When you start hunting for the right crypto card, the first instinct is to glance at flashy rewards and ignore the fine print. That’s a mistake; a hidden fee can erode a month’s worth of gains. A solid starting point is browsing trusted resources like cryptocardbasics.com, where basics are broken down without jargon. From there, you can map your priorities—speed, security, or spend‑ability—against what each provider actually delivers. That diligence pays off when you compare the subtle differences between providers.

Core Features to Evaluate

Cryptocurrency cards differ primarily in the assets they support. Some restrict you to a handful of top‑tier coins, while others embrace dozens of altcoins and stablecoins. The breadth of supported tokens determines how often you’ll need to juggle wallets before a purchase. If your portfolio spikes with lesser‑known gems, a platform limited to Bitcoin and Ethereum will force constant conversion, costing time and possibly small fees. Choosing a platform that mirrors your asset mix prevents unnecessary swaps and keeps your portfolio intact.

If you value instant conversion, look for cards that process transactions on the blockchain itself rather than relying on a centralized processor. On‑chain swaps can shave seconds off the checkout experience, but they may require a small network fee. Conversely, cards that batch conversions off‑chain often bundle costs, resulting in a more predictable expense. Some users even trade off a modest fee for the certainty of a fixed rate. Decide whether speed or cost consistency wins your vote before you sign up.

Consider the card’s integration with existing financial apps. Platforms that sync with popular budgeting tools let you track crypto spend alongside fiat expenses, painting a holistic picture of cash flow. Without this harmony, you might end up guessing where your tokens vanished after a weekend of dining out. Seamless reporting isn’t just a nice‑to‑have; it’s a guardrail against accidental overspending. A unified view also helps you spot irregular spend patterns before they become costly.

Meanwhile, the underlying network choice matters. Cards built on slower chains can lag during peak congestion, leaving merchants with a “transaction pending” message that feels forever. Speedier ecosystems like layer‑2 solutions or sidechains often deliver a smoother checkout, though they sometimes sacrifice decentralization. Opting for a sidechain can shave seconds off each purchase, a marginal gain that adds up. Weigh the trade‑off between raw performance and the philosophical foundation of the blockchain you trust.

A robust customer support framework rounds out the feature set. When a transaction fails or a token freezes, rapid assistance can mean the difference between a missed flight and a missed payment. Look for platforms that offer 24/7 chat, clear escalation paths, and multilingual staff. Support that’s merely an email ticket system buried under generic FAQs rarely meets the demands of active crypto users. Responsive support teams often provide live demos that walk you through the most common hiccups.

Security and Privacy Considerations

Because crypto cards sit at the intersection of digital assets and traditional payment rails, they inherit security concerns from both worlds. Multi‑factor authentication, hardware wallets, and biometric lockouts are baseline defenses you should expect. Anything less feels like a porch light left on in a dark neighborhood; it simply invites unwanted attention. Strong encryption alone won’t shield you if the back‑end infrastructure is flawed.

Yet even the strongest encryption can be undone by careless user habits. Storing recovery phrases on your phone or sharing PINs with friends undermines the platform’s protective layers. A disciplined approach—offline backups, password managers, and regular audits—keeps the security narrative in your favor rather than the hacker’s. A habit of rotating passwords every few months further fortifies that armor.

Notably, some providers offer insurance coverage that kicks in when a breach occurs, akin to a safety net for your digital vault. This insurance isn’t a blanket guarantee; it typically applies to specific scenarios and may involve claim procedures. Still, the existence of such a program signals a company’s confidence in its own defenses. Check the policy fine print to see which incidents are actually covered.

Behind every secure card lies a compliance framework that can affect anonymity. Know‑Your‑Customer (KYC) and Anti‑Money‑Laundering (AML) processes often require identity verification, turning a pseudonymous crypto experience into a trackable one. If privacy is a top priority, research how much personal data the issuer retains and whether they share it with third parties. If anonymity outweighs compliance for you, seek providers that offer minimal data retention.

Often, the most overlooked threat is the merchant itself. Some retailers still process crypto payments through intermediaries that store transaction hashes, opening a backdoor for future data mining. Choosing cards that route payments directly to the blockchain reduces this exposure, but demands that merchants support such direct paths, a rarity in many regions. Direct blockchain routing also reduces the chance of transaction replay attacks.

User Experience and Accessibility

Rarely does a crypto card feel as intuitive as a mainstream credit card, but the gap is shrinking thanks to mobile‑first design philosophies. Apps that streamline onboarding, auto‑populate address fields, and provide real‑time exchange rates help bridge the learning curve. A clunky interface, by contrast, can discourage even seasoned traders from using the card in everyday life. An onboarding tutorial that walks you through the first transaction can turn curiosity into confidence.

Design Matters

Directly after login, the dashboard should reveal key metrics: balance, pending transactions, and rewards earned, all in a glance. Overloading the screen with charts and jargon forces users to hunt for basic information, a friction point that turns curiosity into abandonment. Simplicity does not mean stripping features; it means curating them for immediate relevance. The layout should also allow one‑tap access to the swap feature, streamlining the process.

Still, the tactile feel of the physical card cannot be ignored. Chip quality, magnetic strip durability, and even the card’s visual aesthetic influence how often you carry it in your wallet. A flimsy card that bends after a few weeks conveys a lack of investment in the product, subtly prompting users to revert to their fiat alternatives. A well‑designed card also fits comfortably in a standard wallet slot, avoiding bulk.

Ultimately, accessibility extends beyond the app into regional availability. Some platforms restrict cards to certain countries, forcing users to rely on proxy services or wait for future rollouts. Global reach matters for digital nomads and travelers who expect seamless card acceptance across borders, just like any airline loyalty card. A card that works in over a hundred countries truly earns the label of global.

Beyond basic spendability, the card’s ability to integrate with decentralized finance (DeFi) platforms can unlock new use cases. Features like automatic staking, yield farming, or token swaps within the app transform a simple payment tool into an active financial engine. If your strategy includes earning passive income, prioritize cards that weave DeFi hooks into their core. These DeFi‑linked perks turn every swipe into a micro‑investment opportunity.

Rewards, Fees, and Hidden Costs

Unlike traditional credit cards that parade cash‑back percentages, crypto cards often sweeten the deal with token‑based rewards. These rewards can fluctuate wildly with market movements, turning a predictable 1% cash‑back into a speculative gamble. Assess whether the allure of a token reward aligns with your risk tolerance before you chase the hype. However, token rewards can be volatile; a sudden dip may erase the perceived gain.

Some platforms levy conversion fees each time you spend a crypto asset, a small bite that adds up over a month of coffee purchases. Others bundle the fee into the exchange rate, making it less visible but no less present. Spotting these hidden costs requires a keen eye on transaction receipts and the platform’s fee disclosure page. Scrutinize the fee schedule before you sign up, because hidden costs quietly erode returns.

Every card issuer also imposes a baseline maintenance charge, often waived after you hit a spending threshold. While a modest monthly fee may seem negligible, it can erode the value of modest rewards, especially if you’re not a high‑spender. Weigh the fee structure against your typical monthly outlay to gauge net benefit. If you’re near the waiver threshold, a few extra purchases can flip the equation.

Those loyalty programs that lock rewards for a period can be a double‑edged sword. On one hand, they encourage long‑term holding of the native token, potentially increasing its value. On the other, they restrict immediate redemption, leaving you with idle assets that could have been deployed elsewhere. Lock‑in periods also limit liquidity, meaning you can’t sell the token when the market spikes.

Most users overlook the impact of merchant fees on the final price. When a retailer accepts crypto, they may pass on a processing charge that appears as a slight markup on your receipt. This practice can neutralize any nominal reward you earn, making the entire transaction essentially cost‑neutral. Being aware of these surcharges lets you decide whether the convenience outweighs the extra cost.

Future Outlook and Choosing Your Card

Few crypto cards have yet proven staying power beyond the initial hype cycle; many launch with fanfare only to fade as market conditions shift. Longevity hinges on the issuer’s ability to adapt to regulatory changes, integrate emerging blockchain standards, and sustain a user‑friendly ecosystem. Providers that weather bearish cycles often emerge stronger, having refined their risk models.

Such adaptability is evident in platforms that regularly roll out software updates, expand token support, and partner with global payment networks. A living product that evolves with the crypto landscape offers a hedge against obsolescence, ensuring your card remains functional as new chains rise. Such evolution signals a commitment to staying competitive as user expectations rise.

While no single card fits every scenario, a pragmatic approach is to list your top three priorities—be it speed, security, or reward type—and match them against the providers that excel in each. Treat the selection process like a portfolio diversification exercise: spread risk, capitalize on strengths, and keep options open. Balancing these factors yields a strategic choice that fits both your lifestyle and investment goals.

Across the board, community feedback serves as a reliable barometer for real‑world performance. Forums, social media threads, and user reviews often surface quirks that official documentation glosses over. Tuning into that collective voice can save you weeks of trial and error. Community sentiment also highlights any recurring support delays or outage patterns.

This final checklist: verify supported assets, test transaction speed, confirm fee transparency, and ensure robust support. With those boxes ticked, you’ll wield a crypto card that truly amplifies your digital spending, not just a flashy novelty. Check each item twice before you commit, and you’ll avoid costly surprises.

CONTACT US

Neon

Sunexus Apartments at Pompano

Flagami

880 Townhouses

672 Triplex

Casavista 984

Dadeland House

Schenley Park

Vista to the Plaza

Sovereign Homes

Lora Residence C, D, E, F (4 units)

Copy of 1012-UPDATE_241112 (1)

Gardens on the Roads 1012

Madeira Xenith construction

Madeira

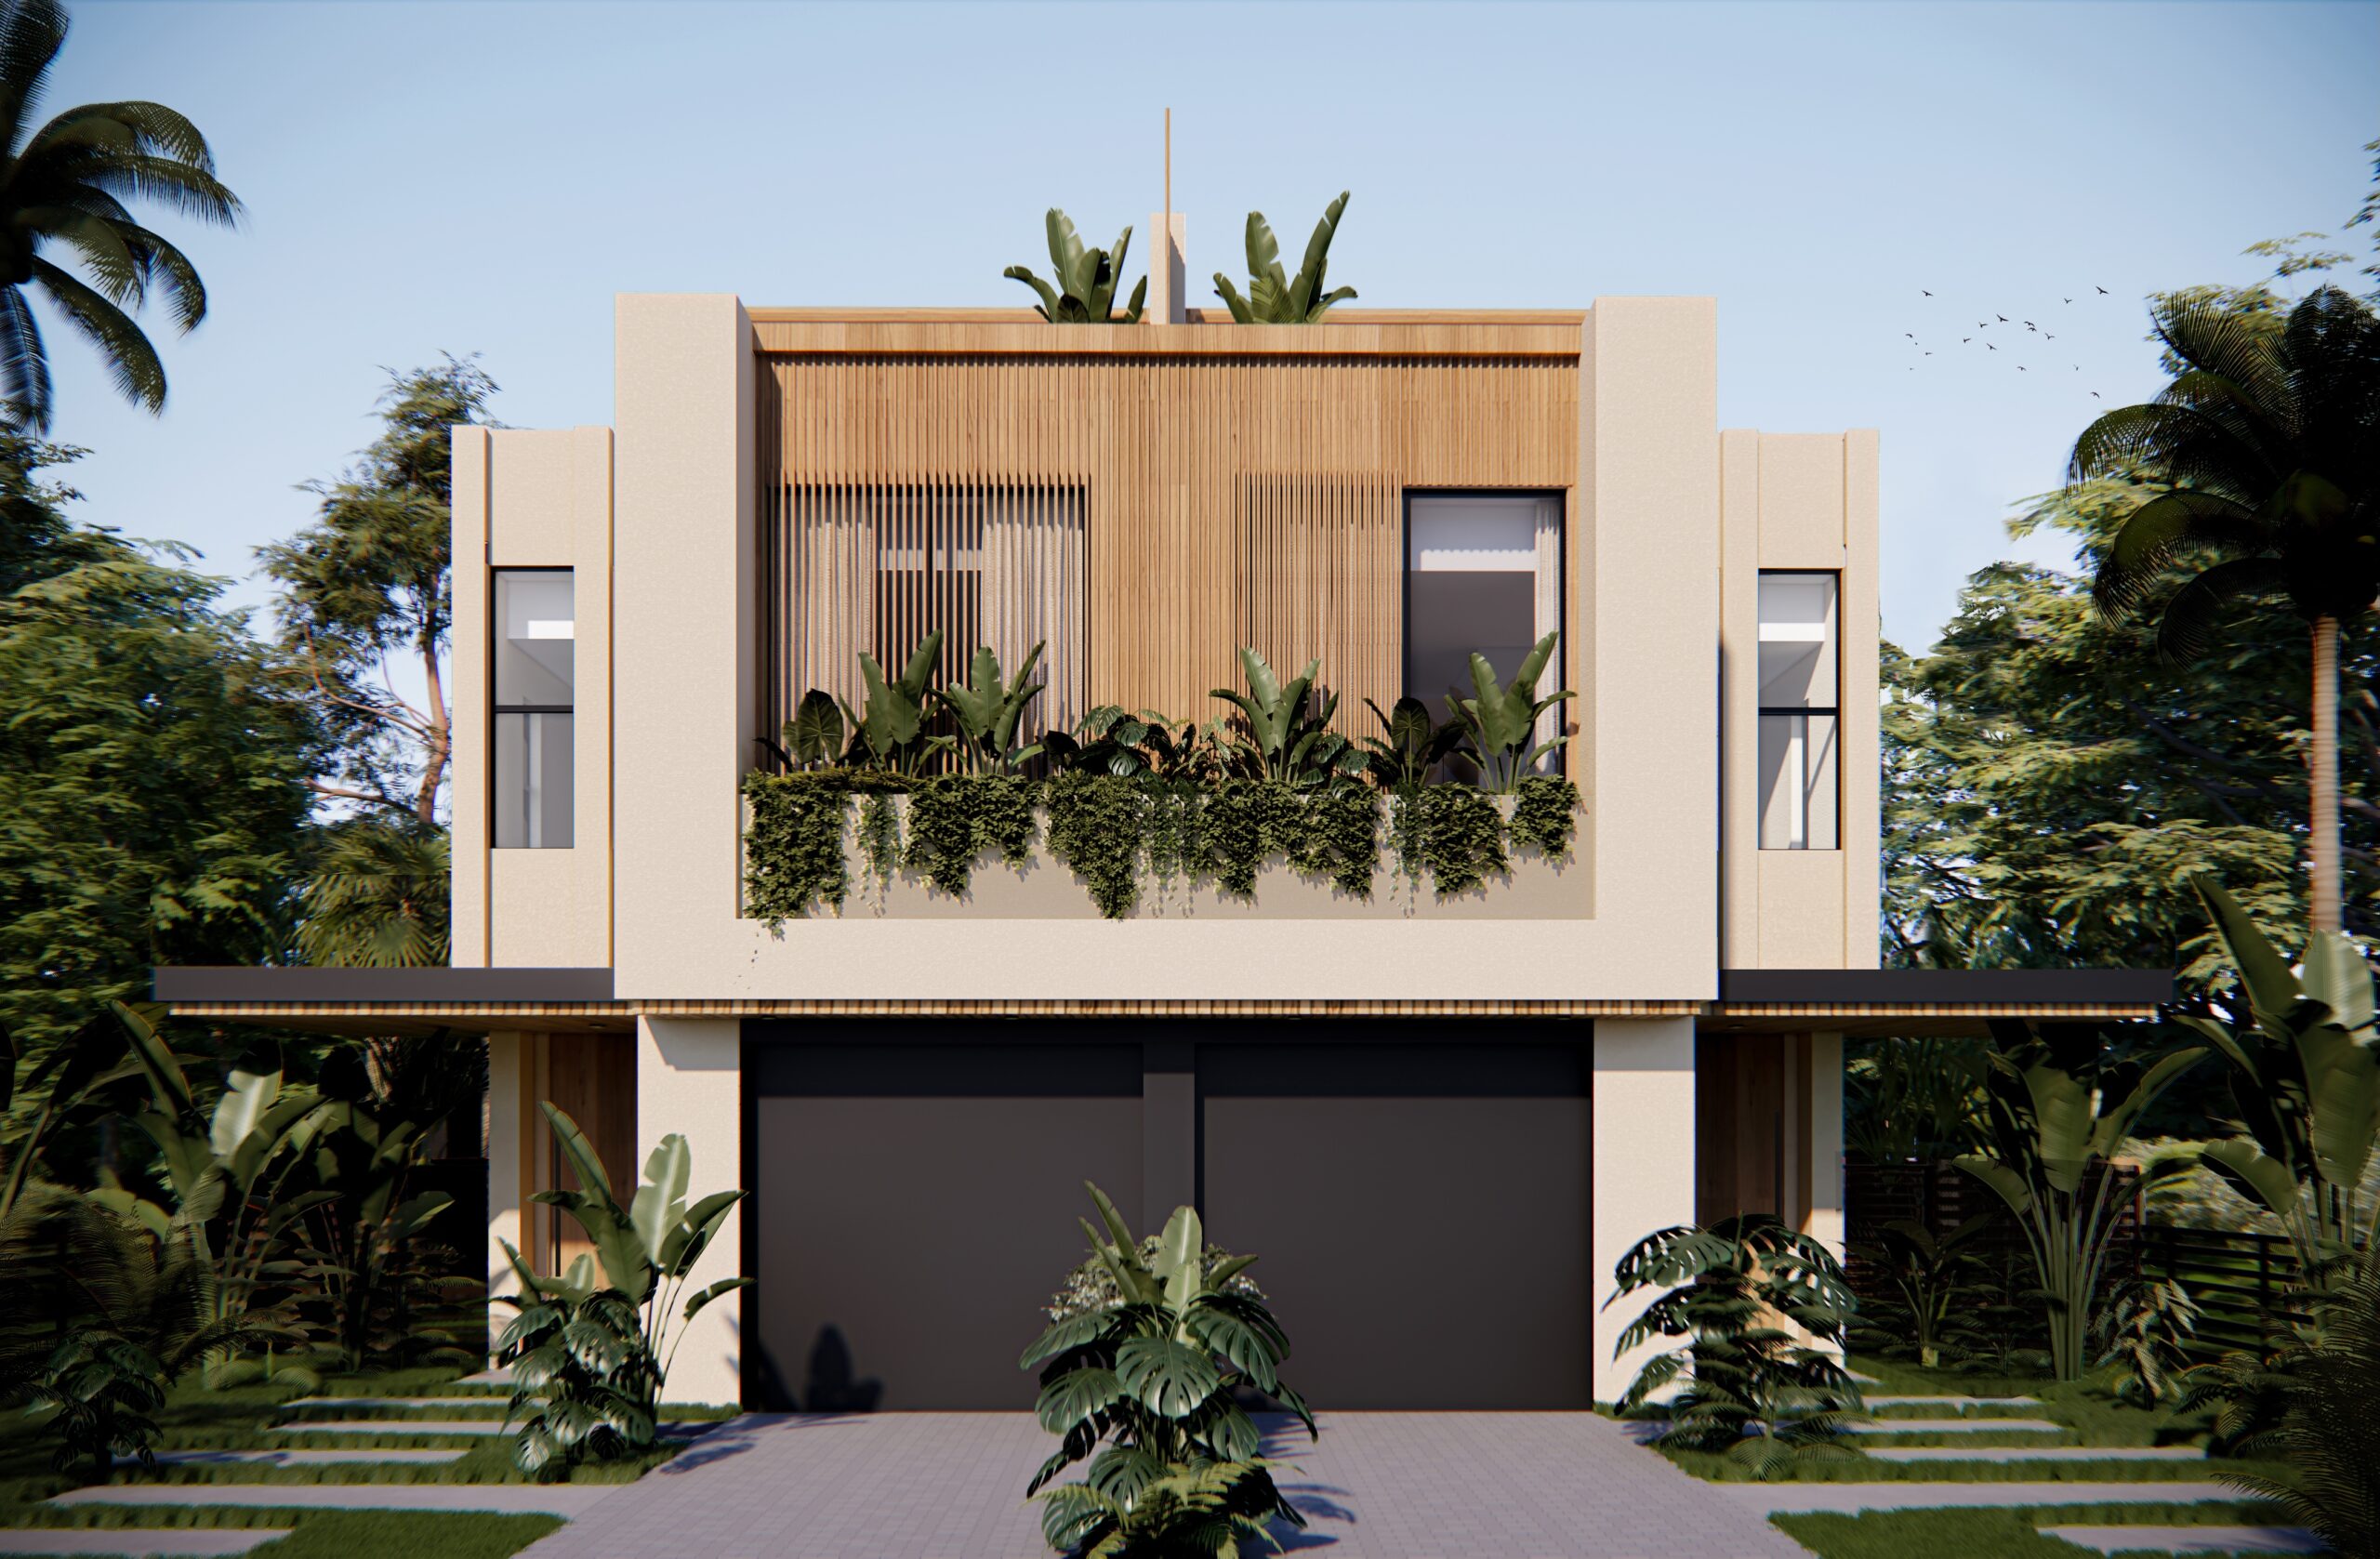
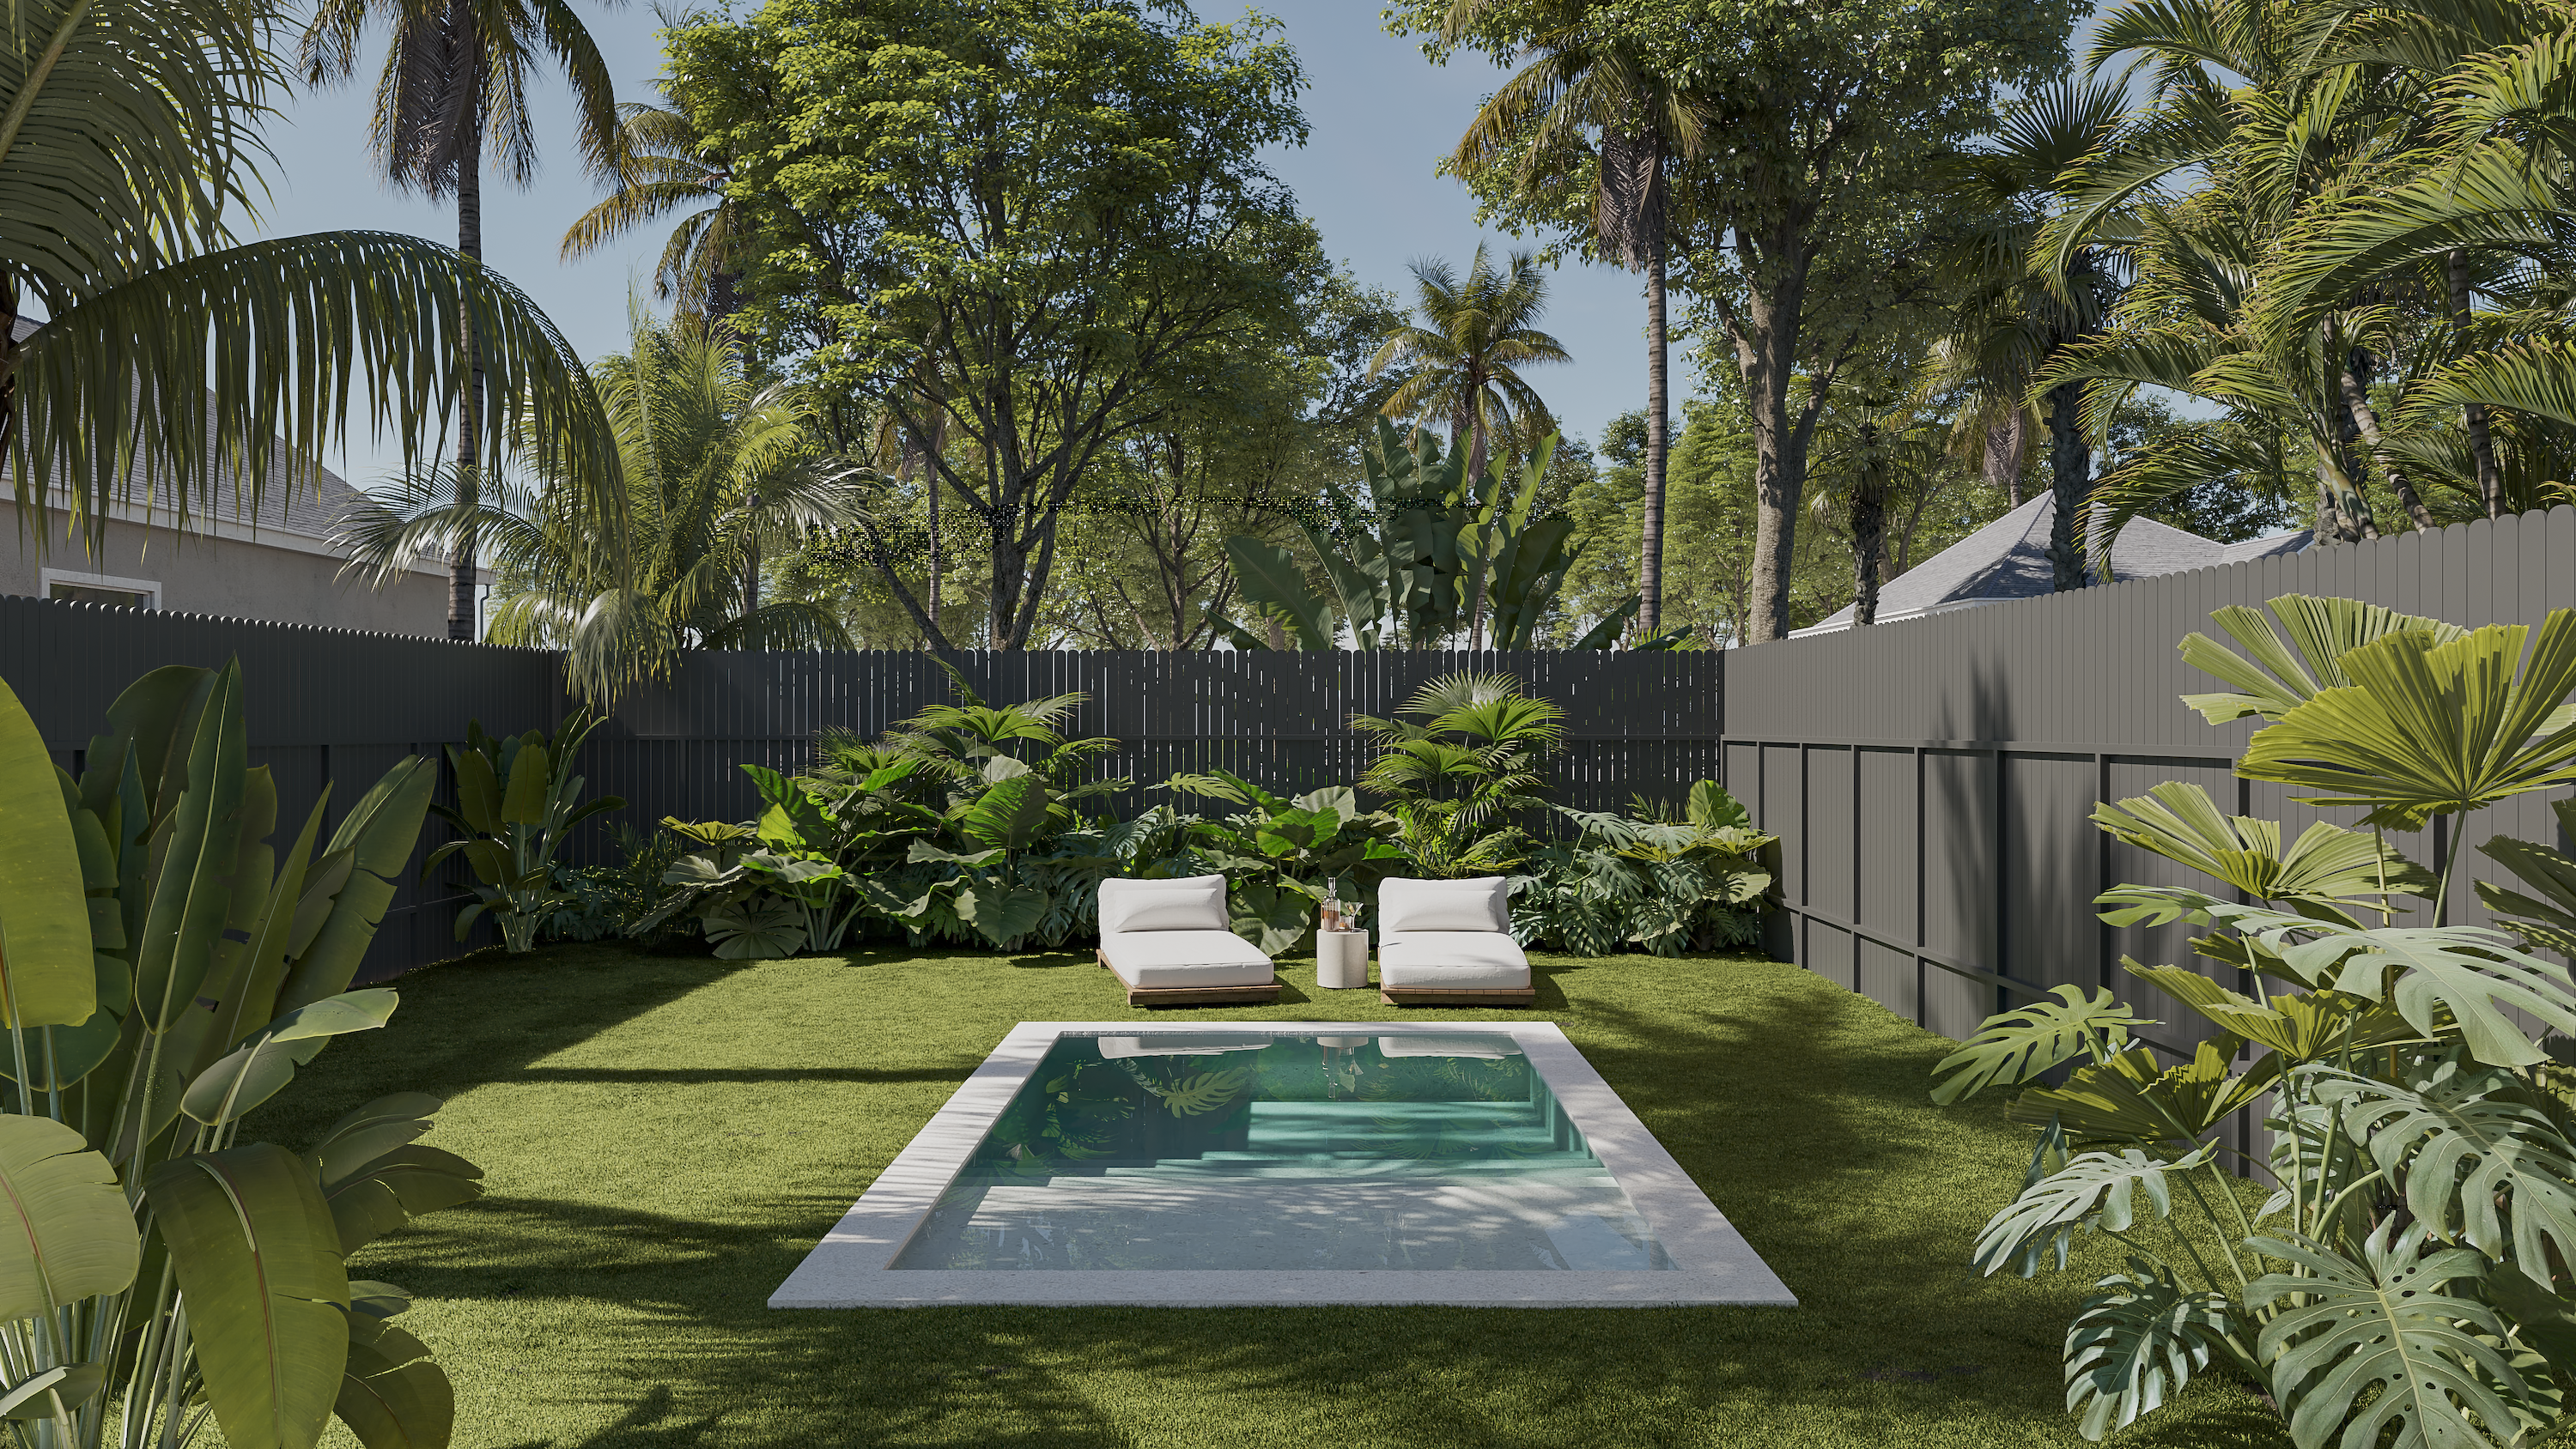
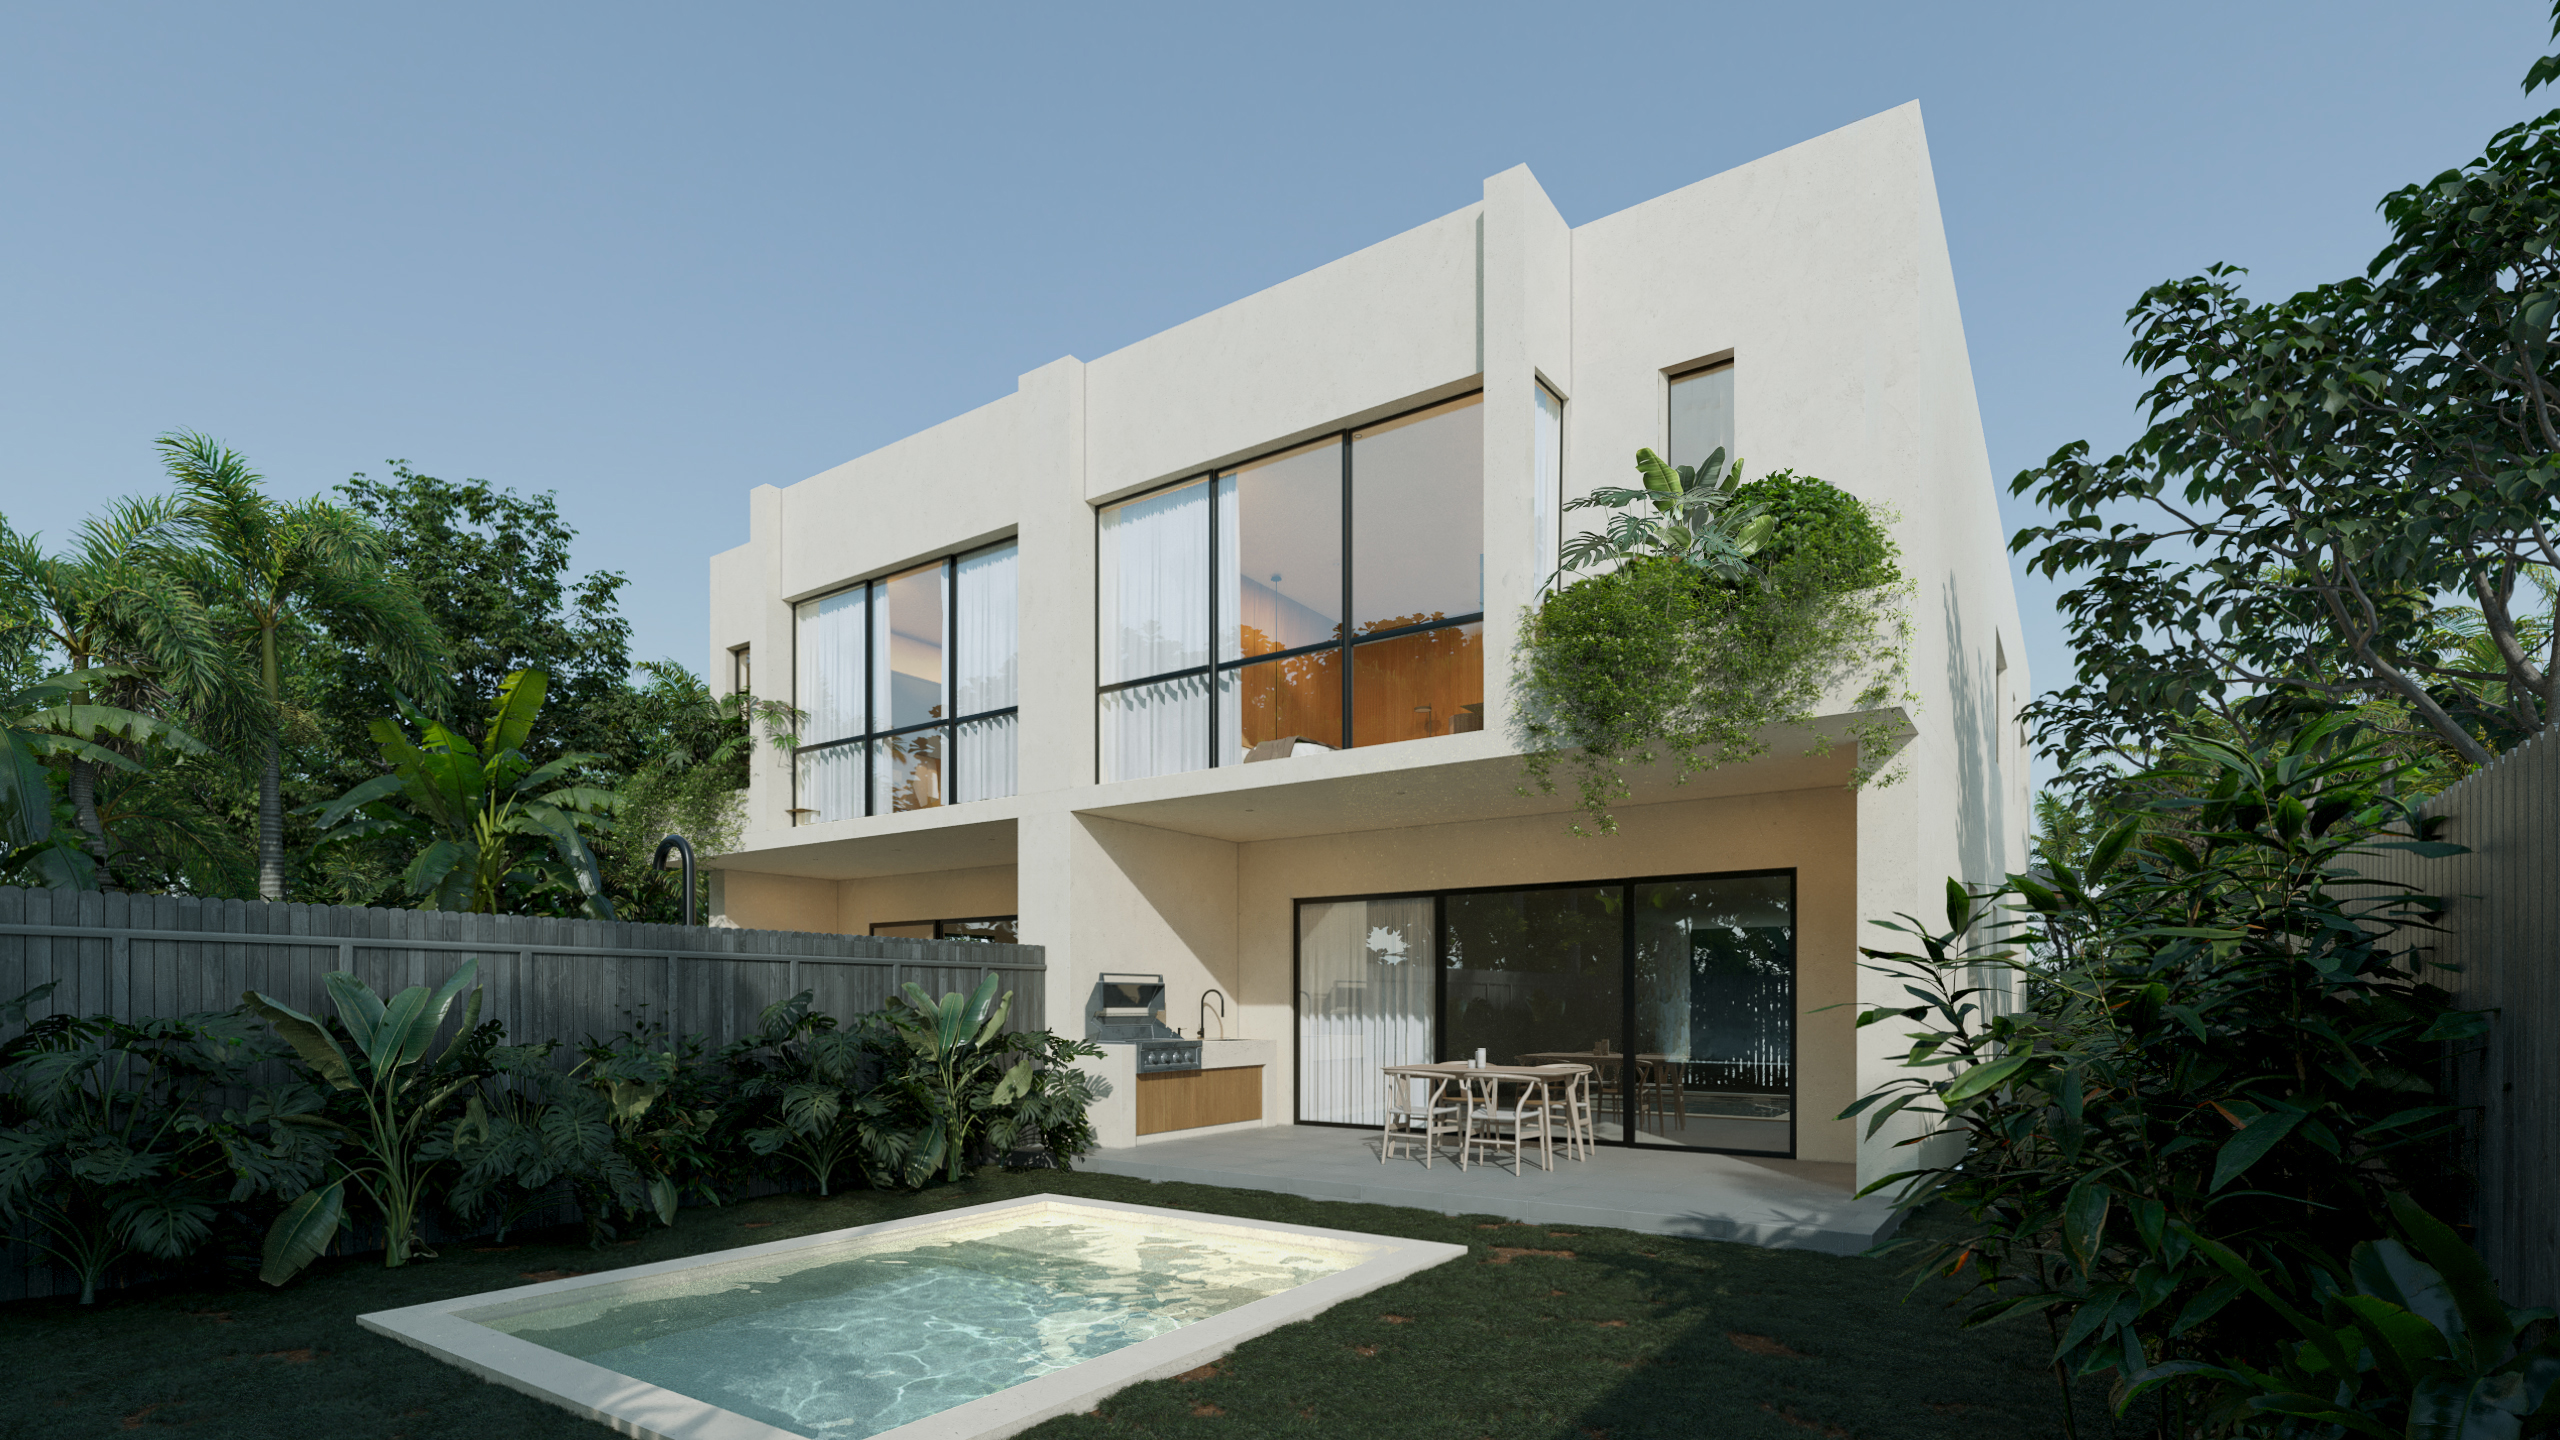
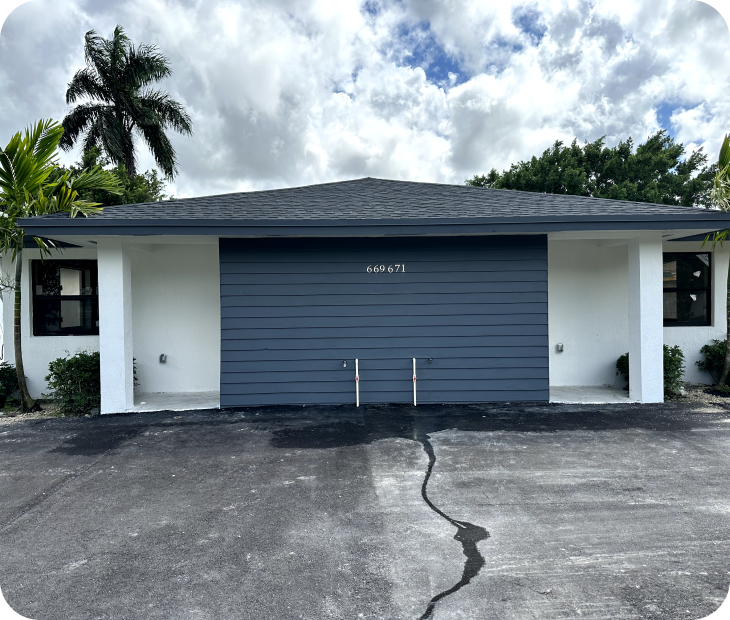
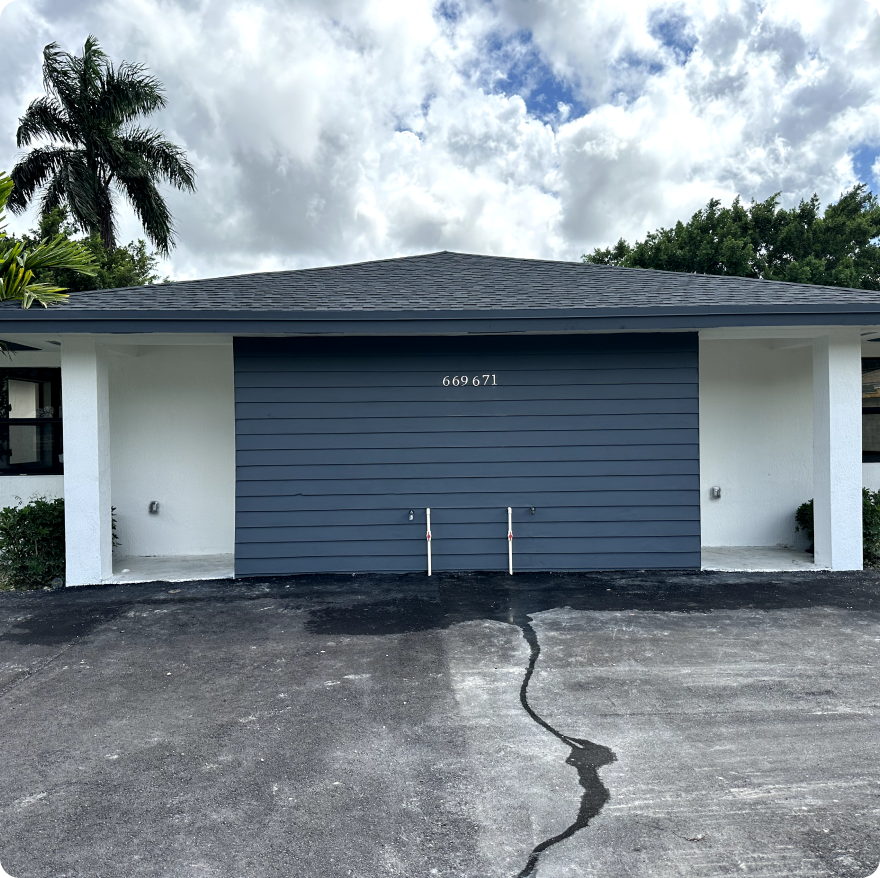
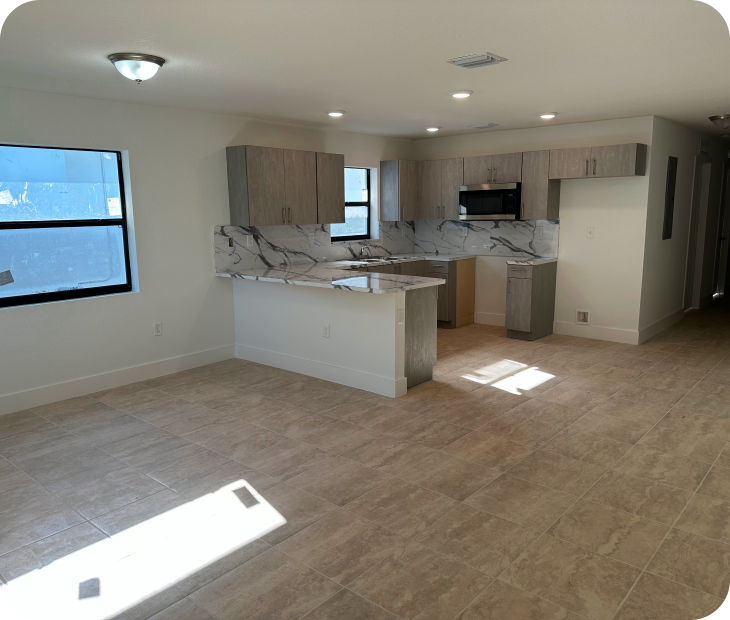
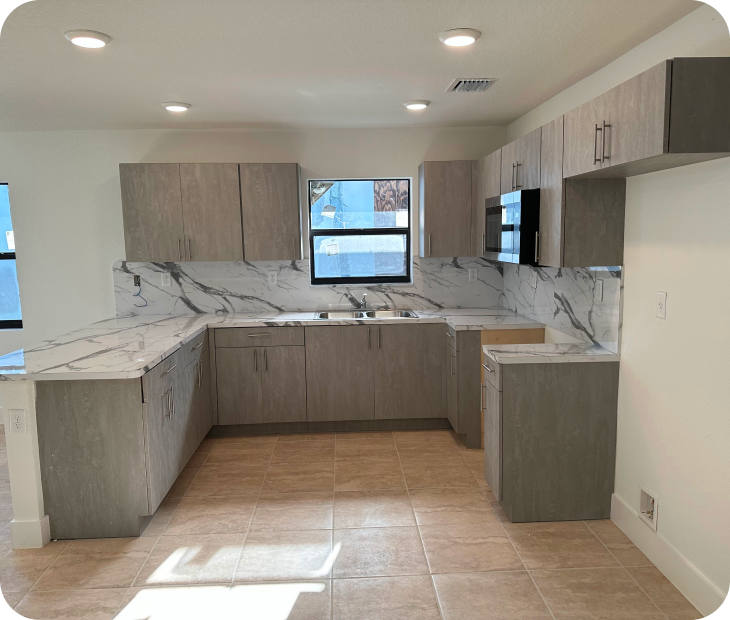
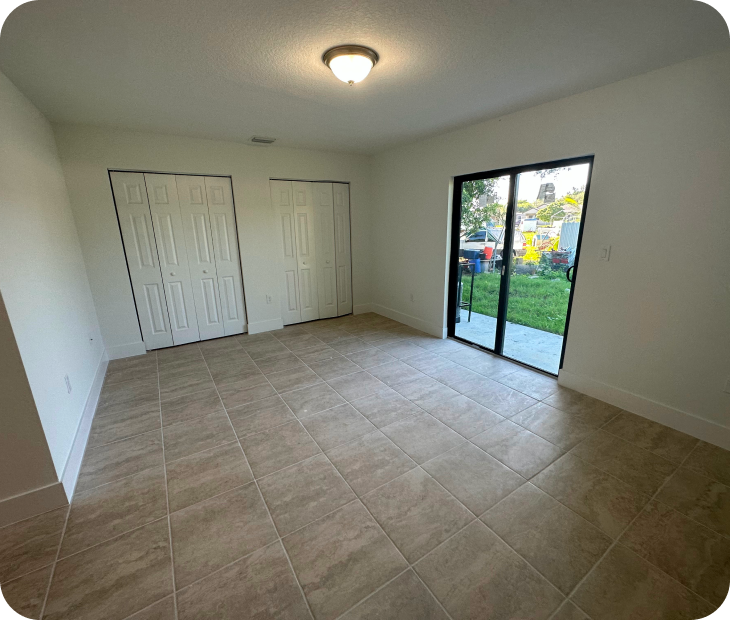
Duplex Florida City Xenith construction

Duplex Florida City

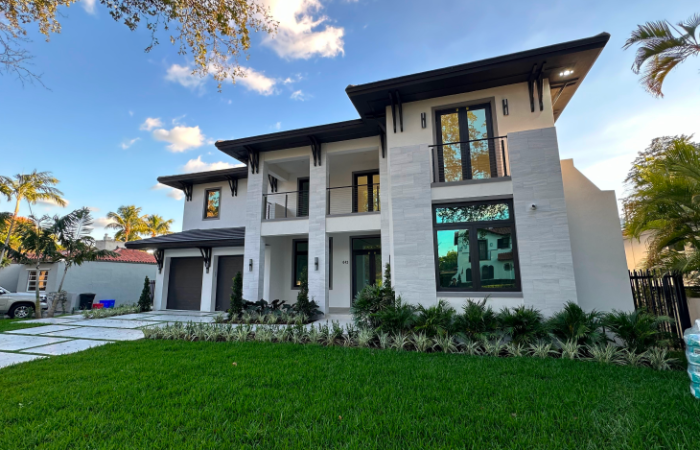
Gables Gate Xenith construction

Gables Gate

Julio Duarte Xenith construction

Julio Duarte

About our CEO:

Julio is a seasoned professional in the Architecture, Engineering, and Construction (AEC) industry, currently serving as the CEO at Xenith Construction. With a career spanning over a decade, Julio has accumulated a wealth of experience and expertise across various roles including Construction Manager, Sustainable Construction Consultant, and Design Coordinator. His dedication and skill have consistently led to remarkable achievements in each of these positions.

«My passion lies in green building science, where I’ve garnered extensive knowledge of sustainable design, building systems commissioning, and certification programs like LEED, NGBS, and EDGE.

As a trusted advisor, I’ve overseen the successful completion of more than 19 million square feet of built area in residential and commercial projects.

I’m deeply committed to sustainable construction. My leadership extends to my tenure as Co-Founder and ex-Chief Operations Officer of CUATROPLANOS, a construction and green building consulting company in Colombia.

My expertise and dedication drive Xenith Construction to excel in every project we
undertake, shaping spaces that inspire and endure.»

Julio holds a Civil Engineering degree from the prestigious Universidad de Los Andes in Colombia, along with a Master of Science degree in Building and Architectural Engineering from Politecnico di Milano. In addition his credentials include certifications as a Florida Certified General Contractor, NGBS Green Verifier, LEED AP BD+C, LEED AP O+M, and WELL AP. His commitment to sustainable construction is evident in his work and leadership.

Julio’s deep understanding of green building practices and his strategic vision for Xenith Construction are driving forces behind the company’s success in creating enduring and inspiring spaces.

Duplex Florida City Xenith construction
Madeira Xenith construction
Gables Gate Xenith construction